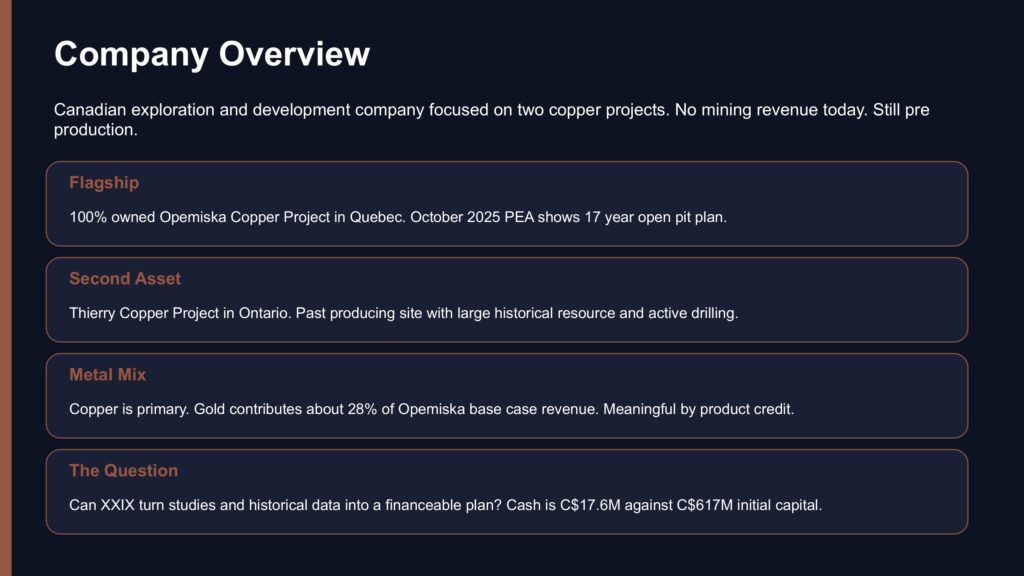
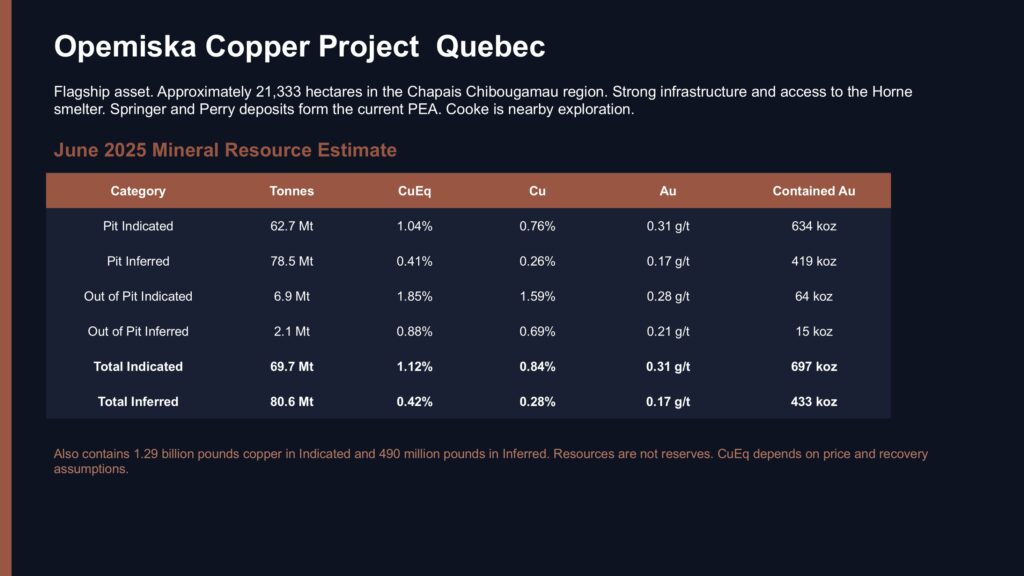
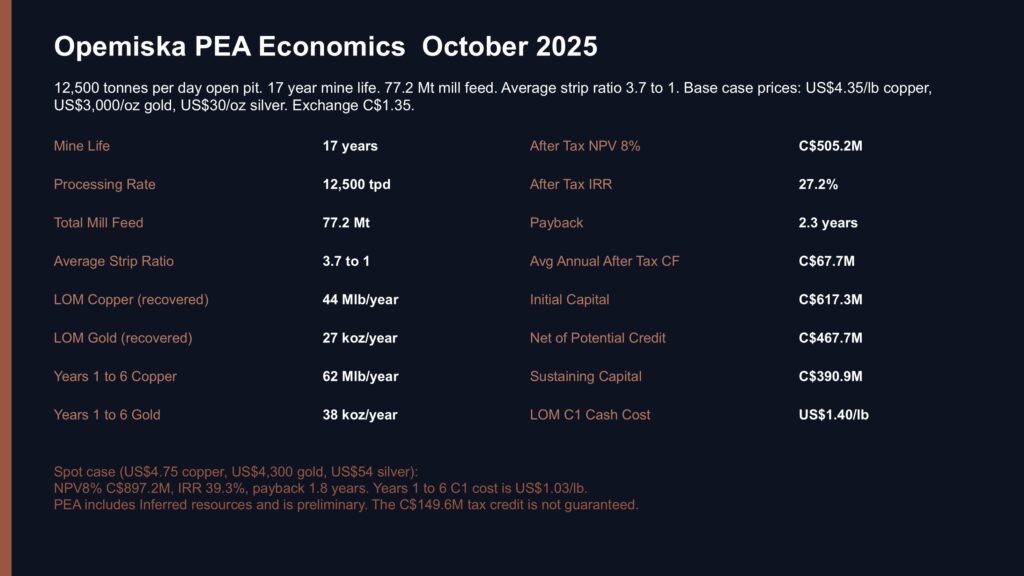
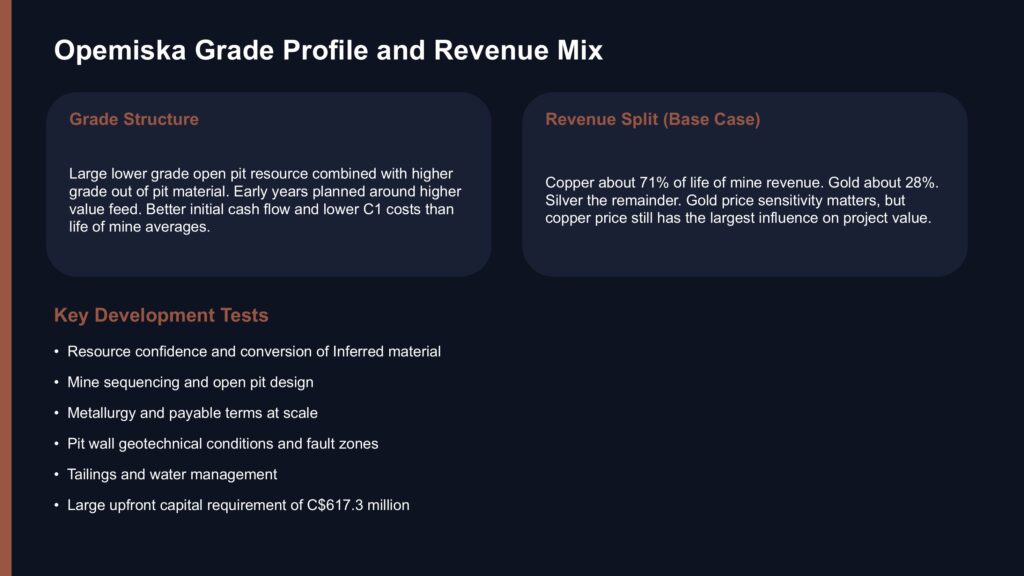
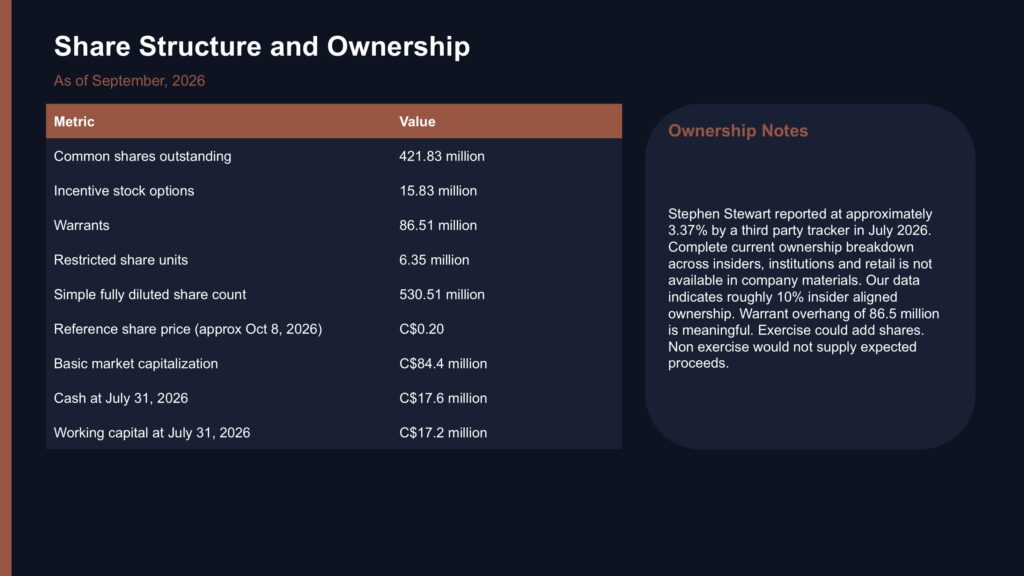
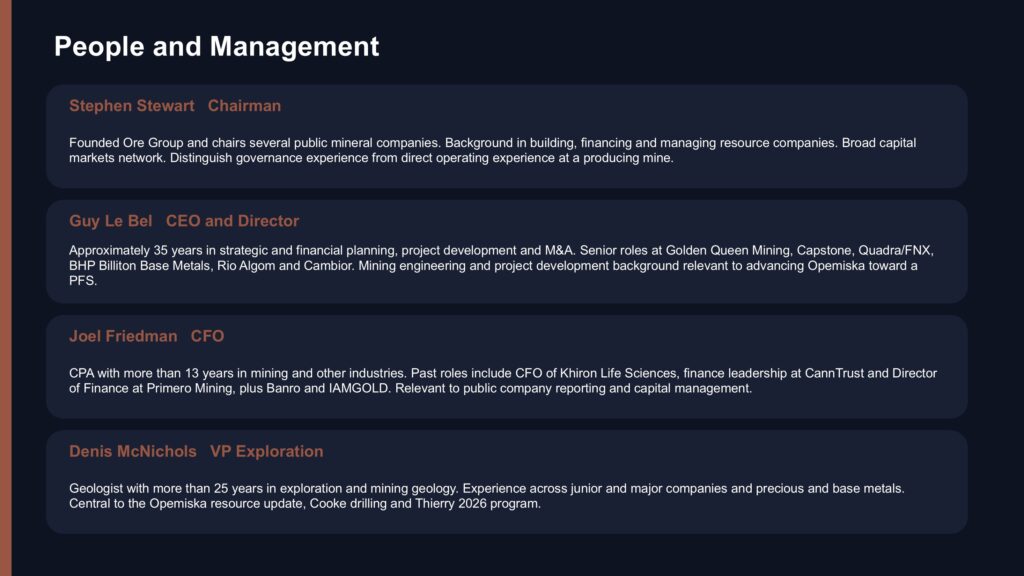
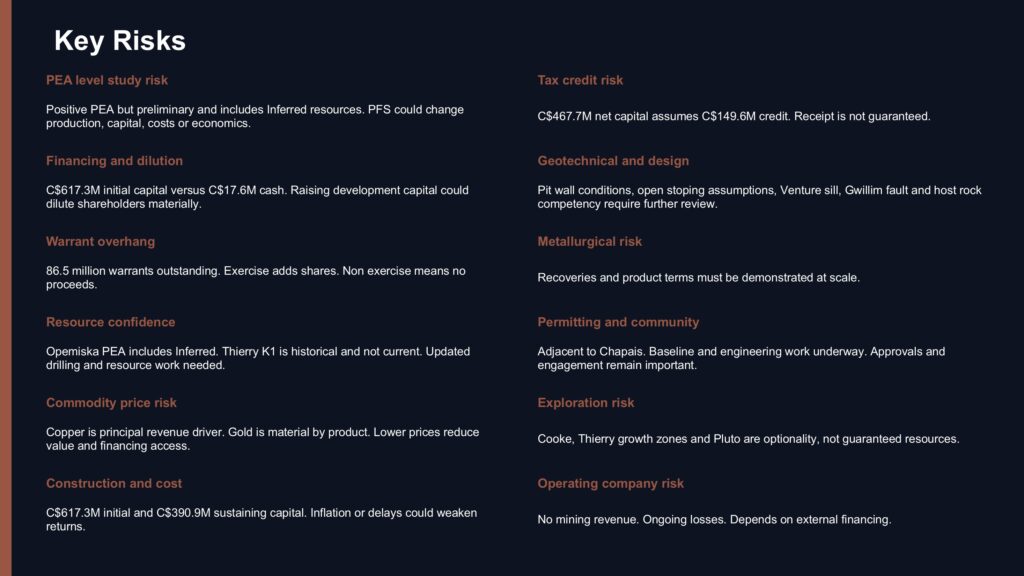
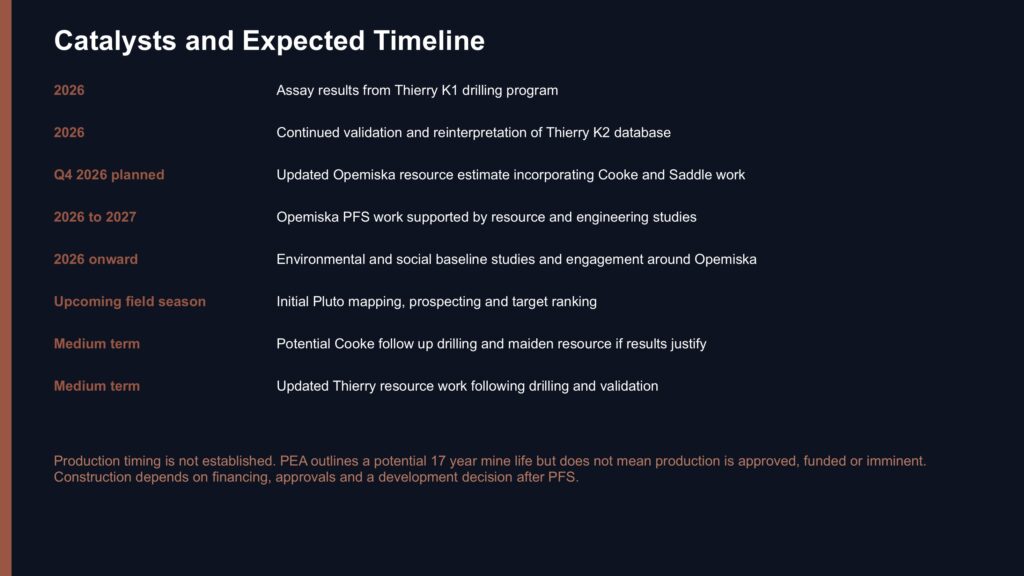
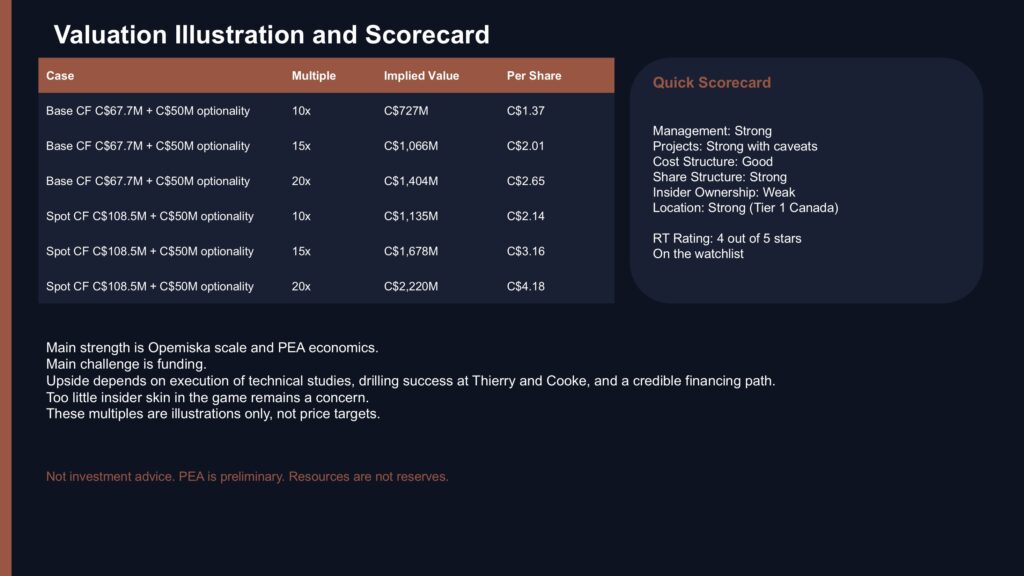
In this episode of deep dive, we breakdown XXIX Metal (TSXV: XXIX), a Canadian copper developer with 2 main assets, Opemiska in Quebec and Thierry in Ontario. The opemiska’s October 2025 PEA outlines a 17-year, 12,500-tonne-per-day open pit, an after-tax NPV of C$505 million, a 27.2% IRR, and gold as roughly 28% of revenue. We then check the resource, PEA math, Cooke drilling, insider ownership, and what has to happen before this C$0.20 story can re-rate. Not investment advice. View the full series to learn more.
Presentation slides:
Full written analysis at the original article here:
https://www.rocketeller.com/xxix-metal-17-year-copper-gold-mine-plan-27-irr-massive-funding-gap/